 3 hours ago
10

The post How to Compare Checking Accounts: An Introductory Guide appeared first on Penny Pinchin' Mom.
Initially, the decision of which checking account to open might seem less consequential than choosing a savings account. This is true, as savings account balances are usually higher, and the money has more of an opportunity to grow. However, this doesn’t mean that checking accounts are all interchangeable. It’s still important to research and pick the best one for your financial situation and preferences.
Checking accounts can vary in fees, interest rates, ATM access, in-person support, and more. Here are some questions you should weigh when comparing checking accounts.
What Is the Type of Checking Account?
There are different types of personal checking accounts for different banking needs. The first thing you’ll want to do when shopping for a new checking account is determine which category would be the best fit for you.
A traditional checking account usually comes to mind. This is your standard checking account, including features like check writing, a debit card, ATM access, and digital banking. Traditional checking accounts are straightforward to open and are widely available at both brick-and-mortar and online banks.
On the other side of the spectrum, there are premium checking accounts, which are designed for those with higher balances. They can come with exclusive benefits like waived fees, a free safe deposit box, and wire transfers. These types of accounts are alternatively known as relationship checking, as more personalized customer support is available compared to what you would get through a traditional account.
Other checking accounts you may encounter during your search are high-yield checking, rewards checking, student checking, senior checking, and second-chance checking. High-yield checking accounts offer higher interest rates than most other types, while rewards checking accounts can come with perks like cash back, airline miles, or reimbursement for ATM fees. Student and senior checking accounts can have reduced fees for their respective age ranges. And in case you have a poor banking history, a second-chance checking account could be your only viable option.
What Are the Checking Account Fees?
Even though certain types of checking accounts, like rewards or premium accounts, may sound attractive, the caveat is that these can come with higher fees. Even with a traditional checking account, you need to consider the fee structure it offers to avoid paying more than you intended.
Common checking account fees include:
Maintenance fees: Some checking accounts charge monthly fees to keep the account open. Maintenance fees can range from $5 to $15 or more, with higher fees associated with higher-interest accounts. Overdraft fees: If you have overdraft coverage, your bank will cover a transaction even if you don’t have enough funds in your account to do so on your own. These fees can stack up quickly. They’re usually around $20 to $30 dollars and may be charged every day that your balance remains negative. Non-sufficient funds (NSF) fees: Similar to overdraft fees, banks charge NSF fees when there aren’t enough funds in an account to cover the cost of a transaction. However, the bank rarely covers the charge.A good way to differentiate between the two is that overdraft fees usually apply to debit card transactions, while NSF fees are for checks, electronic payments, or other payment types. Even though the bank isn’t covering the charge in this case, there’s still a hefty fee involved, sometimes hovering around $20.
Out-of-network ATM fees: If you withdraw cash from an ATM that’s outside your bank’s network, you could get hit with a small fee. In-network ATM withdrawals are mostly free. Some banks reimburse you a certain amount of ATM fees a month. Foreign transaction fees: Banks often charge a percentage-based fee, around 3%, for international purchases. Wire transfer fees: Fees for sending a wire transfer are usually between $25 and $50. International wire transfers are costlier than domestic wires. Paper statement fees: If you receive paper statements rather than digitally, there can sometimes be a small charge. Dormant account or inactivity fees: If there is no activity in your account for six months to a year, you could face a monthly inactivity fee, which can be anywhere from $5 to $20.Sometimes the account will be fee-free by default, while on other occasions you will need to meet certain criteria to have the fee waived, such as by exceeding the minimum balance requirement.
Note – A “no-fee checking account” isn’t entirely without fees, as you may still incur overdraft and other charges.
Are There Any Minimum Balance Requirements?
Some checking accounts impose minimum balance requirements. Sometimes this is a minimum deposit to open the account. Usually, what’s meant by a minimum balance is the lowest amount in your account to avoid monthly maintenance fees or to access certain rewards.
There are a few different ways that banks can define a minimum balance requirement: minimum daily balance, average daily balance, and combined daily balance. A minimum daily balance is based on the amount you have in your account on any given day, and you must meet this threshold every day. The average daily balance is similar, but it’s the average across the statement cycle. Lastly, the combined daily balance factors in the amounts you have across all other accounts at the bank, like savings and CD accounts.
Among checking accounts that have minimum balance requirements, they can frequently be waived, with one common way being to set up direct deposit of your paycheck.
What Is the Annual Percentage Yield (APY)?
APY is the amount of interest you can earn in an account over a year, and it factors in compound interest. This means interest is calculated on your original balance and any interest already earned. Traditional checking accounts have very low APYs, if any at all. For those earning interest, it’s usually below 0.1%.
A high-yield or interest-bearing checking account has APYs sometimes as high as 4% or more. However, these are more frequently associated with higher monthly fees and minimum balance requirements, so you’d have to consider the tradeoffs. Also, APYs can be tiered, meaning that different APYs apply to different balance ranges. Because of this, don’t take the advertised APY at face value. Make sure to read the fine print to see what you would realistically earn.
How Large Is the ATM Network?
If you frequently withdraw cash from your checking account, prioritize checking accounts with large ATM networks, as out-of-network ATM withdrawals can be costly. However, some banks will reimburse out-of-network ATM fees. This can either be a set amount per month, such as $10 or $20, or an unlimited rebate. Reimbursement happens automatically at the end of the statement cycle.
Are There Any Sign-Up Bonuses or Welcome Offers?
Any type of checking account may offer a sign-up bonus or welcome bonus for new account holders. Bonuses can be hundreds of dollars, occasionally going above $1,000. However, you won’t automatically qualify for a welcome bonus, as you usually need to meet several criteria. You may need to deposit and maintain a specified minimum balance, complete a certain number of transactions within a set time period, or keep the account open for a certain length of time.
Does the Bank Have Physical Locations?
Something to weigh when deciding where to open a checking account is whether the bank has physical locations for you to visit or is online-only. Some people prefer banks with in-person access for the more personalized customer service.
However, online-only banks also have their perks. For many, online banking is preferable because of travel or accessibility. In many situations, online banking comes with lower fees than banks with physical locations, but that is not always the case.
What Other Products Does the Bank Offer?
Many consumers prefer all their finances under one roof, as it makes it easy to keep track of funds and access customer support when needed. You’ll want to consider what other financial products your bank offers beyond checking accounts, such as savings accounts, certificates of deposit (CDs), money market accounts, or credit cards. In particular, it’s convenient to have both your checking and savings accounts at the same bank, as many banks offer instant transfers between the two.
What Are the Mobile App Features?
Most reputable banks have mobile apps, though they can differ in features and the overall user experience. Ideally, the app for the bank you’re using will have an intuitive interface, mobile check deposit, strong security features, digital wallet compatibility, accessible customer support, and customizable notifications.
Is the Checking Account Through a Bank or a Credit Union?
Not all checking accounts are offered through banks, as credit unions also provide checking accounts. Banks and credit unions are fairly similar, but they operate differently. Banks are for profit, while credit unions are not-for-profit. Credit unions are more likely to offer higher APYs, so some people prefer them for this reason. However, you usually need to meet some sort of requirement to open an account at a credit union, such as belonging to a certain profession, working at a certain company, or living within a defined area.
Federal insurance works similarly but is through different agencies. The Federal Deposit Insurance Corporation protects money in bank accounts, while the corresponding agency for federal credit unions is the National Credit Union Administration. Smaller state credit unions can be protected by private insurance companies.
What Is the Quality of Customer Service?
In case you encounter an issue with your checking account, you’ll want to choose a bank with strong customer service options, and you may want to look at reviews online. It’s important to contact customer support quickly, and for online banks, this is usually either over the phone or via online chat. In-person banking is also a consideration if you prefer to resolve your issues face-to-face. In-person banking may only be open during regular business hours, while online banking may have extended hours.
How to Compare Checking Accounts Online
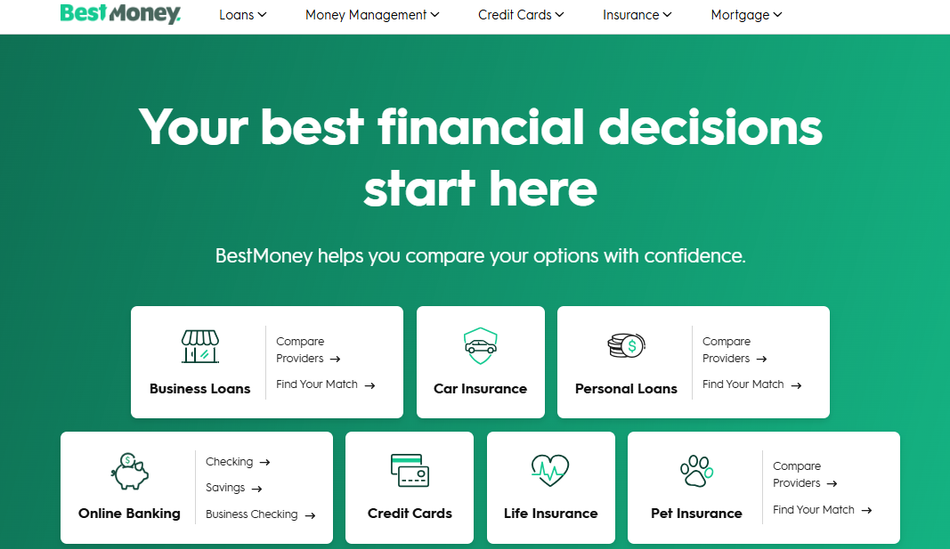
While it’s possible to keep track of all these factors on your own, going to each individual bank’s website isn’t the most efficient way to compare checking accounts. Instead, what many consumers do is use a financial comparison site, such as BestMoney. These sites present you with several options at once, highlight the pros and cons, and provide in-depth editorial ratings and reviews.
Get Started With a Checking Account Today
Whether this is your first checking account or your fiftieth, it’s important to do your research beforehand and compare your options before deciding to open one. Consider factors like fees, rewards, online vs. in-person banking, minimum balance requirements, and ATM networks before making your final choice. Checking account comparison sites can help you narrow down your top picks, and it can be a wise idea to visit several to get a well-rounded view of the banking landscape.
The post How to Compare Checking Accounts: An Introductory Guide appeared first on Penny Pinchin' Mom.
 Bengali (Bangladesh) ·
 English (United States) ·