
 1 hour ago
5

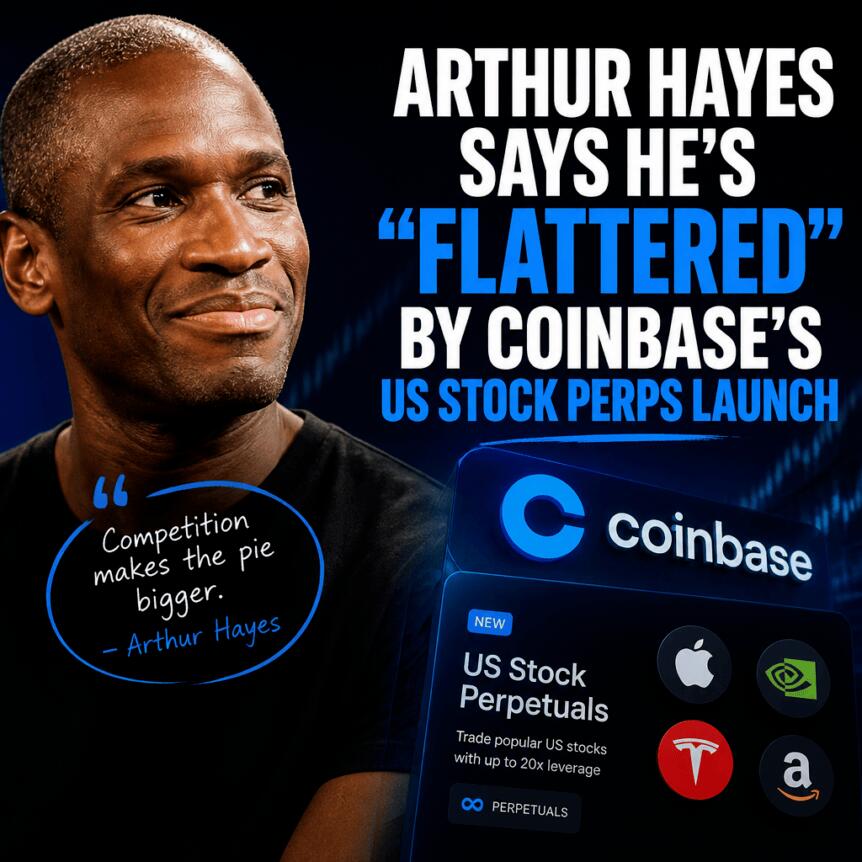
Arthur Hayes, the co-founder of BitMEX, says he is “flattered” by Coinbase’s legal efforts to defend stock-linked perpetual futures in a US court fight involving the CFTC. Hayes made the comments in response to a dispute over whether certain perpetual contracts should be regulated as futures—or instead treated as security-based swaps, which generally face stricter rules for retail participation.
At the center of the case, the Capital Markets Alliance Association (CMAA) is asking the court to stop trading in perpetual futures tied to individual US stocks. Coinbase and five other companies filed a brief opposing CMAA’s request, and the court accepted the submission on Tuesday after it was filed the prior day.
Key takeaways
Hayes framed Coinbase’s position as a decade-later echo of BitMEX’s first perpetual swap launch in the US, saying imitation is “sincere regulation.” CMAA argues stock perpetual contracts should be regulated as security-based swaps due to the way they function for retail traders. Coinbase and other exchanges/market participants oppose CMAA’s effort to temporarily halt trading, and their brief was accepted by the court. The SEC reportedly weighed in by opposing the temporary stop while reviewing how exchanges list these products and whether they qualify as futures or security-based swaps. Judge Valerie Caproni previously denied CMAA a temporary restraining order, citing insufficient proof of likely irreparable harm.Coinbase and allies push back on CMAA’s bid to pause stock perpetuals
The current phase of the dispute follows CMAA’s argument that perpetual futures tied to individual stocks should fall under securities regulation rather than the CFTC’s futures framework. In Monday’s court filing, Coinbase joined five other companies in submitting a brief opposing the alliance’s request to block trading in the contracts. The court accepted the filing Tuesday.
Hayes, who previously led BitMEX when it launched its Bitcoin perpetual swap, said he viewed Coinbase’s participation as evidence that the idea has become mainstream enough to draw serious regulatory attention. He recalled that BitMEX’s 2016 perpetual swap rollout triggered what he characterized as a cooler response from Washington at the time, contrasting that with the current federal court posture involving Coinbase and stock-perpetual offerings.
The significance for market participants is that regulatory classification directly affects the compliance obligations exchanges must satisfy—and how readily retail customers can access similar products. If CMAA prevails, the practical outcome could be tighter constraints or changes to product structure for stock-perpetual trading venues. If CMAA does not, the CFTC’s approach may remain intact for now.
Why classification matters: futures vs. security-based swaps
CMAA’s core claim is regulatory: it argues that the contracts should be treated as security-based swaps, a category that is generally subject to more restrictive retail trading rules. Perpetual contracts add another layer of complexity because they are designed to allow trading without a fixed end date. Unlike traditional futures, “perpetual” structures typically do not settle at a predetermined expiration.
In a Tuesday court filing, CMAA argued that the CFTC approved the contracts without adequately explaining its decision and without addressing unresolved regulatory questions. The alliance also cited reported volume data shortly after the launch of Kalshi’s stock perpetuals—claiming roughly $375 million in reported 24-hour notional trading volume. CMAA used that activity as evidence that the products were already diverting trading from traditional stock markets.
While notional volume is not the same as actual profits or market share, such numbers are often used in court filings to show demand patterns and potential competitive effects. For traders and exchange operators, the practical question is what framework governs listing approvals, marketing restrictions, and investor protections.
The SEC’s reported stance and the court’s prior ruling
According to the report referenced in the underlying coverage, the US Securities and Exchange Commission submitted a proposed brief on Monday opposing CMAA’s request for a temporary halt. The SEC’s reported position was that it was still reviewing exchange rules for listing the contracts, and it did not resolve—at least in that brief—whether those rules should be set aside or whether the products qualify as security futures or security-based swaps.
Separately, a key procedural moment already shaped the dispute. On Nov. 3, US District Judge Valerie Caproni denied CMAA’s request for a temporary restraining order. The court decision hinged on CMAA’s failure to demonstrate likely irreparable harm at that stage. The judge also indicated that CMAA appeared likely to succeed on its argument that the CFTC exceeded its authority—meaning the case can continue even though the immediate trading pause was not granted.
This matters because temporary restraining orders are designed to prevent harm before a final decision. The court’s denial suggests that, at least for now, the legal burden of proving imminent and non-compensable damage has not been met—even if the substantive regulatory argument has some traction.
Perpetual structure and the “no expiry” problem
Stock perpetuals allow traders to speculate on individual share prices without owning the underlying stocks. The absence of a fixed expiration or delivery date is one of the most debated aspects of whether these products resemble futures contracts closely enough to fall under the CFTC’s authority.
Wojciech Kaszycki, a strategy adviser to BTCS SA, told Cointelegraph that the lack of a fixed expiration or delivery date could complicate arguments for treating perpetual contracts as futures. He also warned that a ruling against the CFTC could push trading activity toward offshore and decentralized platforms.
His point—framed as “the product doesn’t die; it just changes address”—captures a tension regulators face in these cases: even when US-based venues face limits, trading demand can migrate to other jurisdictions or platforms. For investors, the outcome may therefore be less about whether speculation continues and more about where it happens and what protections are available.
As the case proceeds, readers should watch for how courts reconcile the contractual mechanics of perpetuals with the legal boundaries between futures regulation and securities-based swap oversight. The next steps in the litigation will likely turn on whether judges accept CMAA’s framing of the contracts as securities-related instruments—and how that interacts with the agencies’ ongoing review of listing rules.
This article was originally published as Arthur Hayes Says He’s “Flattered” by Coinbase’s US Stock Perps Launch on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.


 Bengali (Bangladesh) ·
 English (United States) ·