
Most taxpayers will likely never have to worry about the dreaded alternative minimum tax (AMT) as it generally only affects high-income Canadians. But AMT does occasionally arise for more modest income earners who realize a one-time capital gain on the sale of their business, vacation home or on an income property. A Montreal taxpayer found this out the hard way and went to court, twice, to challenge the government’s right to charge him AMT. Before delving into the details of this unusual tax case, here’s a primer on AMT.
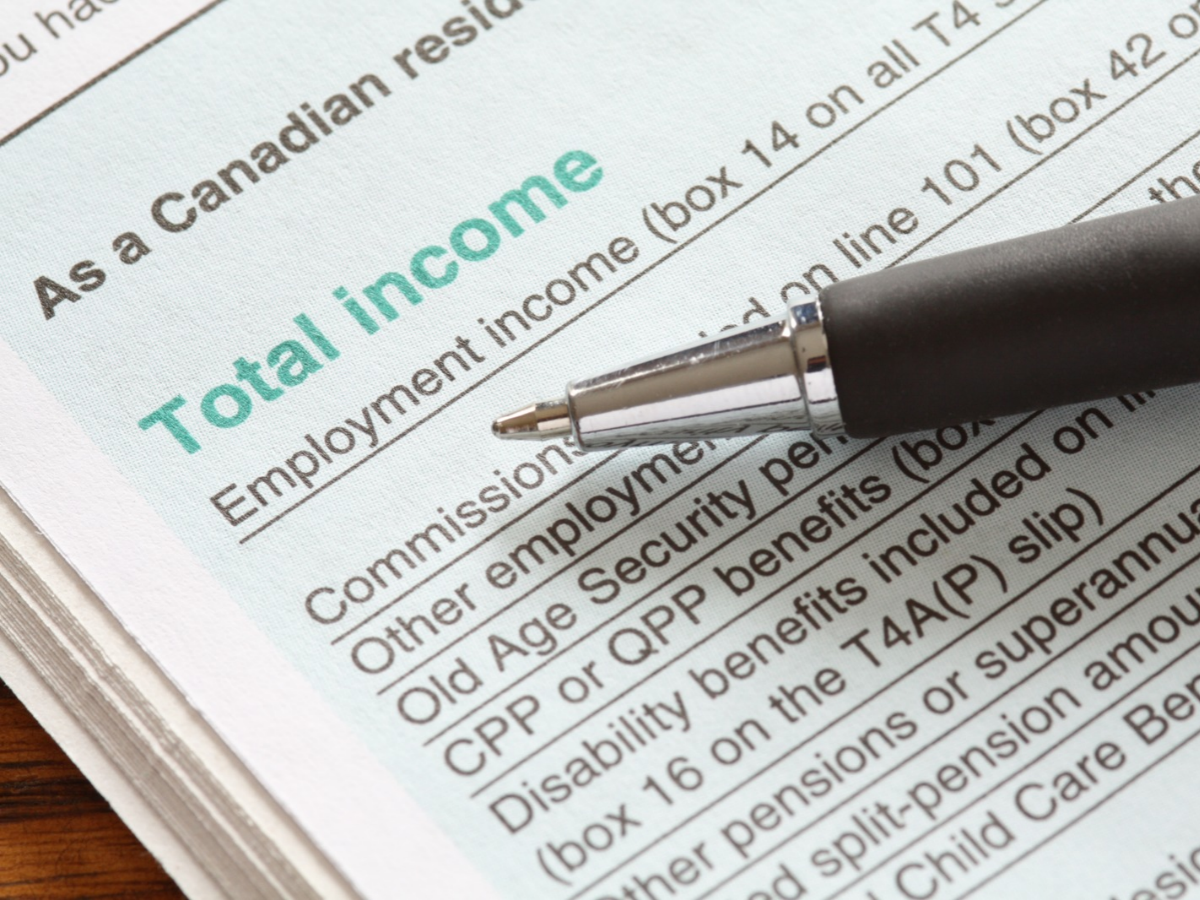
The AMT system imposes a minimum level of tax on taxpayers who claim certain tax deductions, exemptions or credits to reduce the tax that they owe to very low levels. Under the AMT system, there is a parallel tax calculation that allows fewer deductions, exemptions and credits than under the regular income tax calculation . If the amount of tax calculated under the AMT system is more than the amount of tax owing under the regular tax system, the difference owing is payable as AMT for the year.
Changes to the AMT came into effect in 2024 which include: raising the AMT rate; increasing the AMT exemption and broadening the AMT base by limiting certain amounts that reduce taxes (such as exemptions, deductions and credits.) For example, under the regular tax system, only 50 per cent of capital gains are taxable , and you can deduct 100 per cent of any interest expense incurred for the purpose of earning investment or business income. But under the AMT system, taxable income is recalculated such that capital gains are taxable at 100 per cent and deductions (such as interest expense) and credits (such as the basic personal amount) are generally limited to 50 per cent of the regular amounts.
Before 2024, AMT rules applied a flat 15 per cent tax rate on adjusted taxable income. Starting in 2024, the government increased the AMT rate to 20.5 per cent, which equals the rate for the second federal income tax bracket. All provinces and territories also impose AMT, which is generally calculated as a percentage of the federal AMT.
Fortunately, most taxpayers will never come across AMT since the exemption, which was frozen at $40,000 prior to 2024, has now been increased to the start of the fourth federal tax bracket, which for 2026 is $181,440. Because of this exemption, very few Canadians pay AMT under the new rules, and even high-income Canadians may not pay AMT if their only sources of income are fully taxable employment, or professional or business income.
If you do end up paying AMT, you may be able to get it back over the following seven years to the extent your regular tax exceeds AMT in those years, but the recovery of AMT paid in the past is far from a sure thing.
In the recent case, the taxpayer had realized a capital gain in 2021 of $538,767 and ended up paying AMT of $33,860. While the taxpayer agreed that, according to the wording of the relevant provisions of the Income Tax Act he was required to pay the AMT, he argued that this tax should not apply to him because “he does not belong to the category of high-income taxpayers who abuse deductions and exemptions.” Rather, the capital gain he realized in 2021 was “a one-time event and the income he could earn in the seven years following 2021 will not be sufficient for him to recover the (AMT).”
In 2025, the Tax Court dismissed the taxpayer’s appeal saying that the court’s role is merely to determine whether the Canada Revenue Agency’s assessment of the AMT was correct “ in law and in fact. ” Since the taxpayer agreed that the CRA’s math was correct, the taxpayer was only in court on “a question of principle.”
Unfortunately for the taxpayer, as the lower court judge wrote, “The law is the law, and the (CRA) cannot change the law. … If you believe sincerely … that the law should be amended one way or another … you can write a letter to the Minister of Finance.”
The taxpayer then appealed the Tax Court’s decision to the Federal Court of Appeal which heard the case earlier this month. In his appeal, he argued that the Tax Court erred in law in interpreting the AMT rules “without regard to their purpose or the unfair result to which that interpretation leads in his case.”
The appellate judges acknowledged that the taxpayer was, indeed, correct in noting that one of the objectives of the AMT, as stated in the 1985 federal budget, was to increase taxes on high-income individuals. But, ultimately, it was Parliament that determined the criteria in the Tax Act for determining what constitutes “high income.”
The taxpayer also attempted to argue that the uniform application of the AMT without distinction between “wealthy taxpayers, who can recover the minimum tax, and … average taxpayers, who cannot recover it” is contrary to the Canadian Charter of Rights and Freedoms.
A Canadian who lived abroad thought she followed TFSA contribution rules, but CRA surprised her with a penalty taxHere's what happens to someone's TFSA after they dieBut the court was unable to consider this since a constitutional argument cannot be raised for the first time in an appellate court and the party raising a constitutional question must first notify the attorneys general of Canada and the provinces so that they can respond. This was not done here.
As a result, in a short, oral decision delivered directly from the bench, the unanimous three-judge panel dismissed the taxpayer’s appeal, with the result that the AMT was, indeed, payable.
Jamie Golombek, FCPA, FCA, CFP, CLU, TEP, is the managing director, Tax & Estate Planning with CIBC Private Wealth in Toronto. Jamie.Golombek@cibc.com .
If you liked this story, sign up for more in the FP Investor newsletter.

 Bengali (Bangladesh) ·
 English (United States) ·